The Belt and Road Initiative
The Belt and Road Initiative is the global programme China launched in 2013, covering infrastructure investment along land and sea routes.
The Belt and Road Initiative is the global programme China launched in 2013, covering infrastructure investment along land and sea routes. It now spans 150 countries. The Belt refers to the overland routes and the Road to the sea routes. Construction contracts and investment reached a combined US$1.539 trillion between 2013 and mid-2026, and 2025 was the biggest year so far.[2][7] For seafarers its visible face is the port.
Why China Looked Outward
The roots go back well before 2013. China's aid projects in North Korea, Vietnam and Africa stayed small under Mao. The economy grew after the reforms Deng Xiaoping began in December 1978, and under Jiang Zemin a "Go Out" policy pushed Chinese construction firms abroad.[3] Commentators see several motives behind the initiative. Chinese industry had built up excess capacity that needed markets abroad. Energy routes depended on chokepoints such as the Strait of Malacca, a weakness known as the "Malacca dilemma". Developing Xinjiang, which borders eight countries, was a further aim.[3]
The Astana and Jakarta Speeches
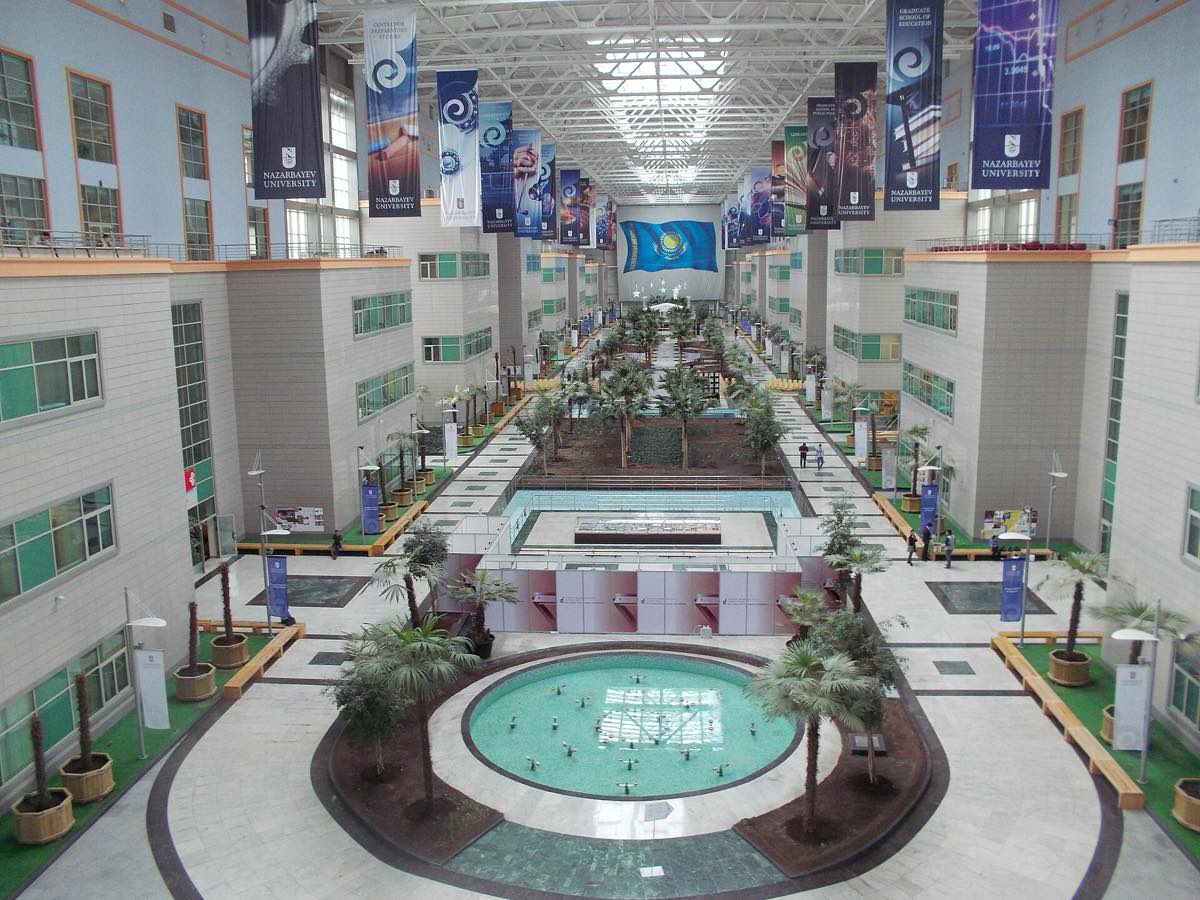
The programme was announced against that background. On 7 September 2013 President Xi Jinping spoke to students at Nazarbayev University in Astana about the old caravan routes across Kazakhstan and proposed a Silk Road Economic Belt along them. A month later, in the Indonesian parliament, he added the 21st-Century Maritime Silk Road.[1] That same October Xi launched the Asian Infrastructure Investment Bank initiative. The bank's founding agreement entered into force on 25 December 2015.[10]
In its early years the programme was called One Belt One Road. Beijing concluded that "one" and "strategy" were being misread, and in 2016 the English name became Belt and Road Initiative. It now consists of six land corridors and the Maritime Silk Road.[3] Joining carries no binding treaty, and countries generally sign a memorandum of understanding.
Piraeus and COSCO
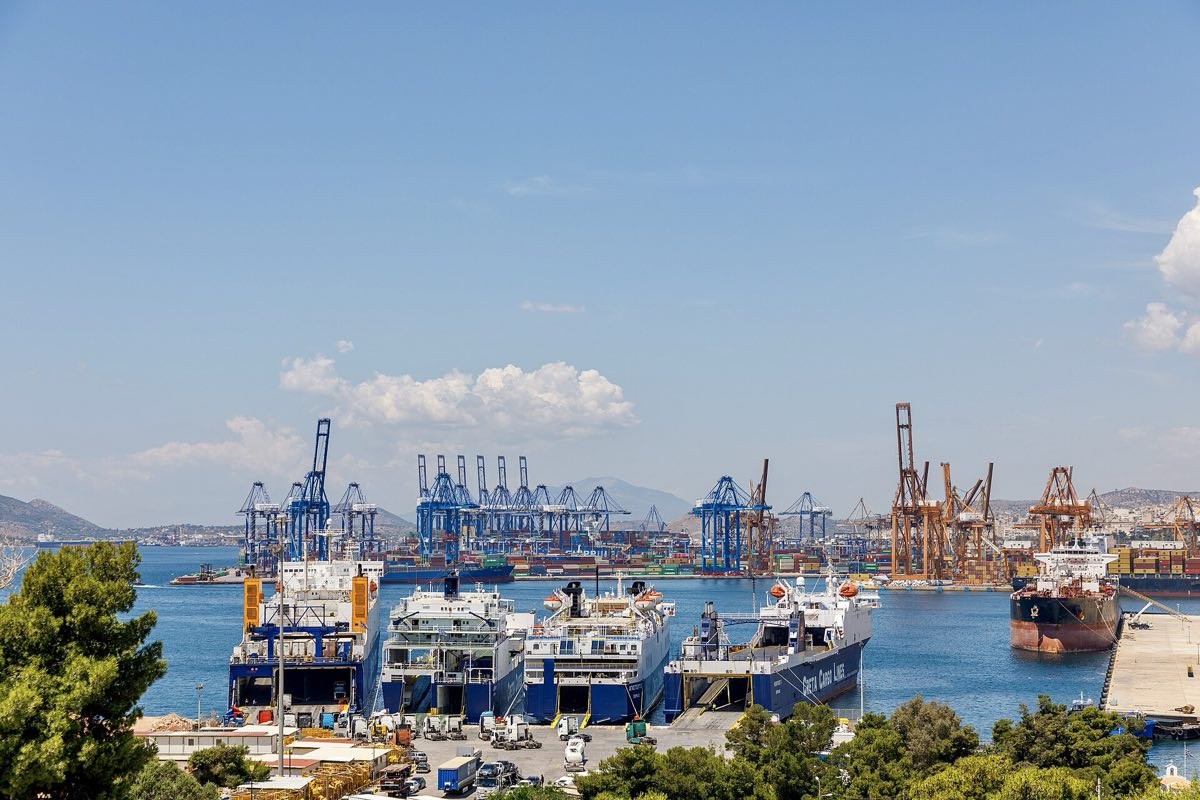
Chinese port operators were abroad before this. COSCO leased the container piers at Piraeus, Greece's largest port, in 2009. When the Greek debt crisis forced state asset sales, COSCO bought 51% of the Piraeus Port Authority in 2016 for €280.5 million, and raised that to 67% in 2021 after meeting its investment conditions.[4] The port peaked at 5.65 million TEU in 2019 and fell to 4.64 million in 2025. The Red Sea crisis, which affected traffic heading for Suez, is thought to have played a part.[4]
Hambantota and the Debt Trap Debate
Hambantota in southern Sri Lanka became the symbol of the argument. The idea of a port there surfaced as a 2001 election promise, and a Canadian-funded feasibility study of 2002 was judged inadequate. Mahinda Rajapaksa, a Hambantota native, was elected president in 2005. His government asked the United States and India for finance and both declined. In February 2007 China agreed to pay.[5]
Construction began in January 2008. China Exim Bank lent US$306.7 million at 6.3% for the first phase and a further US$757 million at 2% for the second. Phase one opened on 18 November 2010, but the expected traffic did not come, and accumulated losses reached 46.7 billion rupees by the end of 2016.[5] The government elected in 2015 renegotiated the deal. In July 2017 China Merchants Port committed US$1.12 billion and took a 99-year lease. That transaction spread the phrase debt-trap diplomacy.[5]
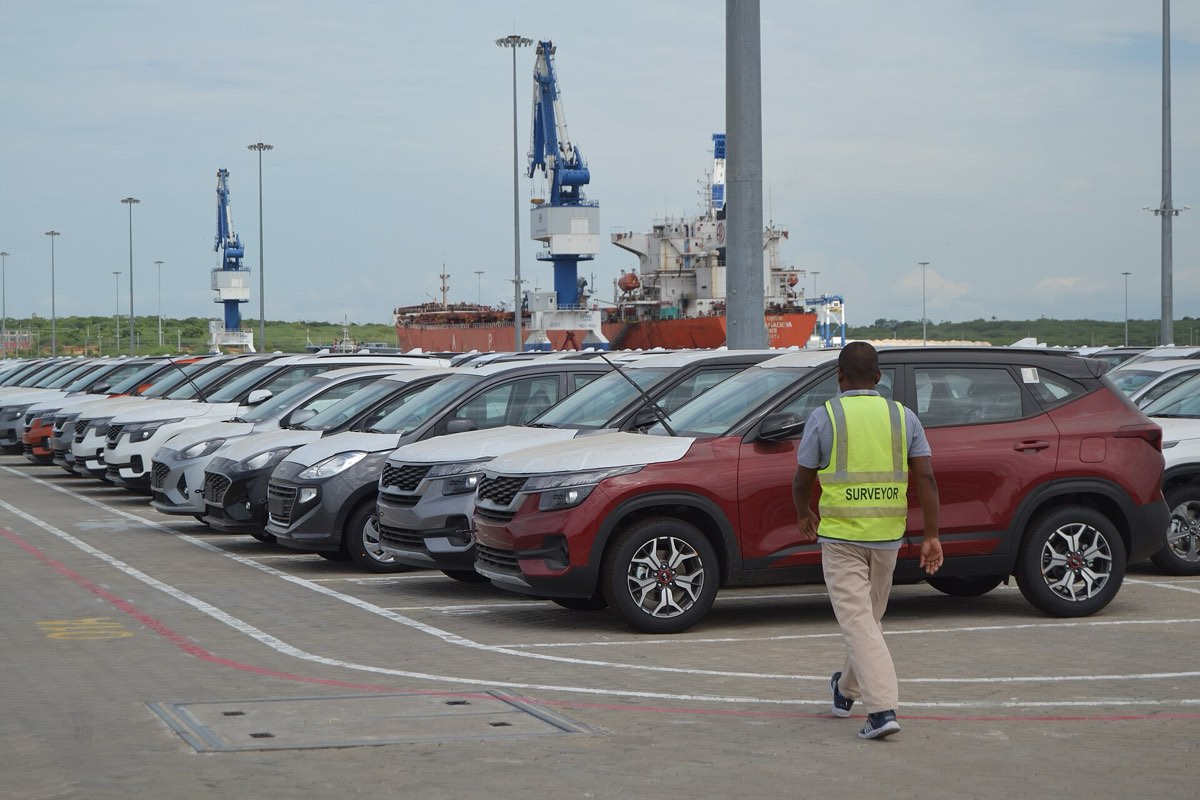
Most researchers reject that reading. They point out that most of Sri Lanka's foreign debt was owed to creditors outside China, and that the lease money went on short-term debts unrelated to the port. The port's commercial case, though, was weak from the start.[5] It later found work in vehicle transhipment, with ro-ro volume of 579,362 units in 2024 and 726,153 in 2025.[9] In 2026 the operator invested US$108 million in six quay cranes and 16 yard cranes.[5]
Gwadar and the Pakistan Corridor
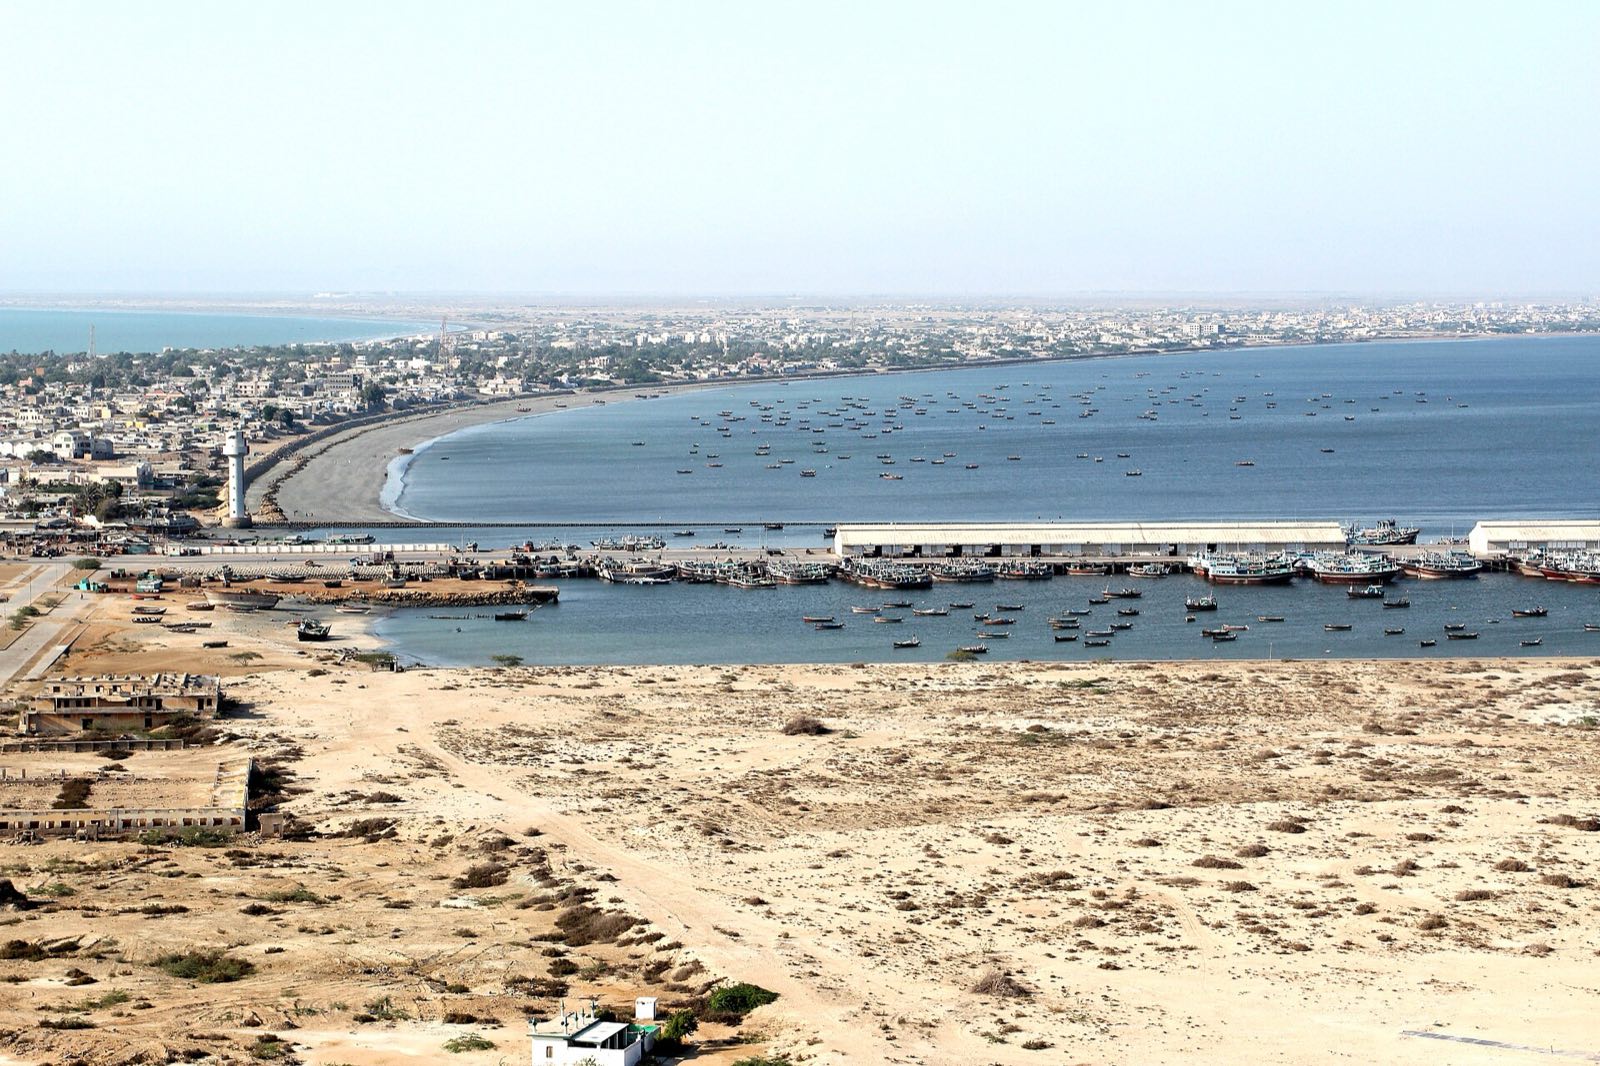
Gwadar in Pakistan has a history much older than the Belt and Road. In 1954 a US Geological Survey researcher identified it as a good port site. It belonged to Oman then, and Pakistan bought it on 8 September 1958 for £3 million. Construction of the first phase began in 2002, with China paying most of the cost. Pakistan gave the operation to Singapore's PSA in 2007, then on 18 February 2013 it passed to the Chinese state company China Overseas Port Holding.[11]
The big project came two years later. On 20 April 2015 China and Pakistan signed a US$46 billion agreement for the China-Pakistan Economic Corridor, with Gwadar as its outlet to the sea.[12] The results have fallen far short. The port handled just 8,300 TEU in all of 2025, and 11,000 TEU in April 2026 with cargo diverted by the Iran war.[11] As of 2026 about 38 of some 90 planned projects were finished, and the Nedopil report recorded no new Chinese engagement in Pakistan in the first half of the year.[7][12]
Kumport and Chancay
Türkiye joined this map in 2015. In September a partnership of COSCO Pacific, China Merchants and CIC Capital paid US$940 million for 65% of Fina Liman, which runs the Kumport container terminal at Ambarlı in Istanbul. Oman's state reserve fund kept the other 35%. At 1.3 million TEU a year it was the country's third-largest container terminal, and the deal counted as the largest Chinese direct investment in Türkiye to that point.[13] So a terminal in Istanbul handling 16% of national container traffic passed to Chinese operators.
Chancay in Peru is a newer example. COSCO took a 60% stake in 2019, and the port opened on 14 November 2024 at a video-linked ceremony with Xi and President Boluarte. The goal was a direct route from South America to Asia. Peru's port authority at first tried to annul COSCO's exclusivity, then withdrew the suit in June 2024.[6][14] The dispute grew in 2026. When a Lima court placed the port beyond the reach of the regulator Ositrán, the United States said Peru was losing sovereignty. A later ruling in July 2026 restored state oversight.[14]
Railways and Debt on Land
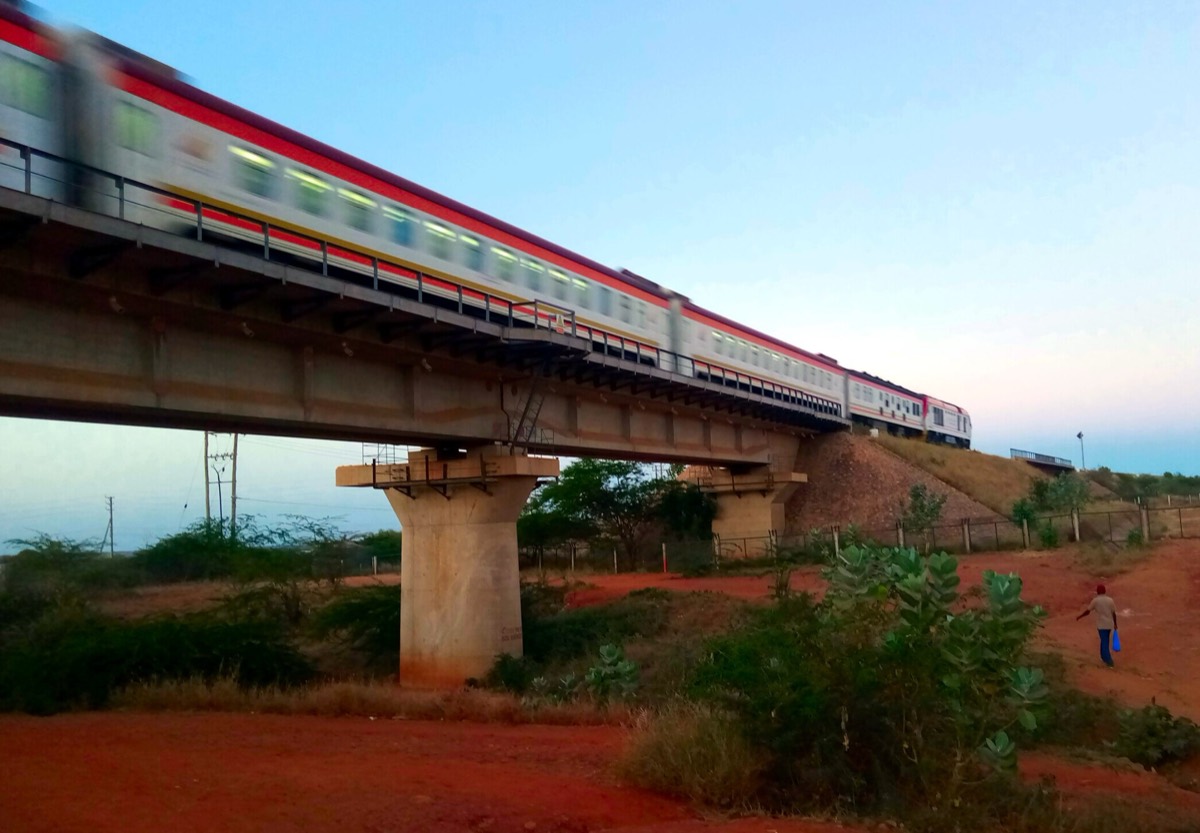
The biggest projects on the Belt side are railways, and the debt argument is more concrete there. Kenya's 472-kilometre Mombasa-Nairobi line opened on 31 May 2017. It cost about US$3.6 billion, 90% of it covered by China Exim Bank. The contract set freight guarantees from the port to the line. In 2019 the government required all cargo cleared at Mombasa to go by rail, and transporters protested. In 2020 operating costs still exceeded revenue.[15]
Laos's 422-kilometre Boten-Vientiane line opened on 3 December 2021. Of the roughly US$6 billion cost, 60% was China Exim Bank debt and the rest came from a joint venture 70% owned by China. Fitch had rated Laos CCC in 2020, citing excessive debt.[16]
Countries That Left or Objected
Debt and politics also brought departures. Italy signed a memorandum in March 2019, the only G7 country to join. The hoped-for exports and investment did not materialise, and its imports from China grew faster than its exports there. Giorgia Meloni's government told Beijing on 6 December 2023 that it would not renew.[17] Panama announced in February 2025, straight after a visit by US Secretary of State Marco Rubio, that it would not extend the memorandum it signed in 2017.[8] The decision belonged to the wider dispute over Chinese influence around the Panama Canal. India objects to the programme because the Pakistan corridor runs through the Kashmir region.[12]
The 2025 Record and 2026
Despite these exits the numbers grew, though the content changed. In 2025 construction contracts came to US$128 billion and investment to US$85 billion. Energy took 43% of the total, a record US$93.9 billion, and more than three quarters of that went to fossil fuels. Metals and mining also hit a record at US$32.6 billion. Transport infrastructure fell to US$13.3 billion, its lowest since the initiative began. Africa rose 283% to US$61.2 billion.[2]
Christoph Nedopil's report of July 2026 confirmed the trend. In the first half of 2026 construction contracts reached US$76.5 billion and investment US$49.8 billion, the highest first half since 2013. For the first time 56% of energy engagement was green. Transport grew for the first time since 2020, to US$18.2 billion, all of it in construction contracts. Africa was again first overall, while the Middle East led construction at US$36.5 billion. The private sector's share rose from 13% in 2020 to 48%.[7] China publishes no official list, so these figures are compiled by researchers from contract and investment announcements.
For a shipowner the Belt and Road appears as the port's operator, its charges and its terminal arrangements. In container shipping, at terminals such as Piraeus, Kumport or Chancay, one group can own both the ship and the berth.
Frequently asked questions
What is the Belt and Road Initiative?
The Belt and Road Initiative is the global programme China launched in 2013, covering infrastructure investment along land and sea routes.
When did the Belt and Road Initiative begin?
Xi Jinping announced the Belt in Astana in September 2013 and the Road in Indonesia in October 2013.
Is Türkiye part of the Belt and Road Initiative?
Yes. The purchase by Chinese companies of 65% of the Kumport terminal at Ambarlı, Istanbul, in 2015 was presented within this framework.
Was Hambantota port a debt trap?
That is disputed. The port was leased to China Merchants Port for 99 years in 2017. Many researchers say most of Sri Lanka's debt was owed outside China and that the lease money went on other debts.
Sources
- Xinhua and Belt and Road Portal. Xi Story: A transformative speech that gave rise to Belt and Road Initiative; University of Southern California US-China Institute.
- Eco-Business. The Belt and Road boomed in 2025, 4 February 2026, with Griffith Asia Institute and Green Finance & Development Center data.
- Wikipedia. Belt and Road Initiative (secondary source).
- Wikipedia. Port of Piraeus (secondary source).
- Wikipedia. Hambantota International Port (secondary source).
- Wikipedia. Port of Chancay; China Global South Project, 15 November 2024.
- Christoph Nedopil. China Belt and Road Initiative (BRI) Investment Report 2026 H1, University of Queensland and Green Finance & Development Center, July 2026.
- Caixin Global. Panama Quits China's Belt and Road Initiative, 8 February 2025.
- The Sunday Times (Sri Lanka). Hambantota Port Records 175% Cargo Growth in 2025, 18 January 2026.
- Wikipedia. Asian Infrastructure Investment Bank (secondary source).
- Wikipedia. Gwadar Port (secondary source).
- Wikipedia. China-Pakistan Economic Corridor (secondary source).
- Invest in Türkiye. Chinese consortium buys into Turkish port with USD 940 million investment, 28 September 2015.
- gCaptain. Peru Concedes in Port Spat with China's Cosco, 25 June 2024, and the 2026 news summaries on the same page.
- Wikipedia. Mombasa-Nairobi Standard Gauge Railway (secondary source).
- Wikipedia. Boten-Vientiane railway (secondary source).
- CSIS. Italy Withdraws from China's Belt and Road Initiative, 14 December 2023.